- How Do You Claim R&D Tax Credits in the UK?
- What Are R&D Tax Credits and Why Are They Important?
- Which R&D Scheme Applies in 2026? Merged RDEC vs ERIS
- Who Is Eligible to Claim R&D Tax Credits in the UK?
- What Research Activities and Expenses Qualify for R&D Tax Credits?
- What Documentation Is Required to Support an R&D Tax Credit Claim?
- Step-by-Step Process for Claiming R&D Tax Credits in the UK
- How to File Your R&D Claim with HMRC: Forms and Deadlines
- Submit the Claim with Your Tax Return
- How Do You Calculate the Amount of R&D Tax Credit?
- What Are Common Challenges When Claiming R&D Tax Credits and How Can You Overcome Them?
- What Are the Benefits of Successfully Claiming R&D Tax Credits?
- Frequently Asked Questions (FAQ)
- Conclusion
Research and Development (R&D) tax credits (also called R&D tax relief) offer innovative UK businesses a valuable, government-backed way to reduce their Corporation Tax by rewarding investments in developing new products, improving organisational processes, or creating new software. Claiming the relief successfully requires understanding HMRC’s eligibility criteria, gathering the necessary documentation, and following the correct application process through your Company Tax Return (CT600).
This guide covers everything about how to claim R&D tax credits, from checking whether your company qualifies to preparing documentation and completing the R&D tax relief application process, helping you maximise your claim efficiently and compliantly. It reflects the merged R&D scheme that applies to accounting periods beginning on or after 1 April 2024, including the claim notification and Additional Information Form requirements.
How Do You Claim R&D Tax Credits in the UK?
To claim R&D tax credits in the UK, confirm your project seeks a scientific or technological advance, send HMRC a claim notification if you are a first-time or lapsed claimant, complete the online Additional Information Form, and include the claim in your CT600 within two years of your accounting period end.
- Check eligibility: your company pays UK Corporation Tax and carries out qualifying R&D.
- Notify HMRC if required: first-time claimants, and companies that have not claimed in the last three years, must submit a claim notification within 6 months of the period end.
- Work out qualifying costs: staff, externally provided workers, consumables, software, data and cloud costs.
- Complete the Additional Information Form (AIF) online before you file the CT600.
- File your CT600 with the R&D claim and computation within 2 years of the end of the accounting period.
- Keep your records ready in case HMRC opens an enquiry.
R&D tax credits and R&D tax relief mean the same thing. Since 1 April 2024, most companies claim through the merged scheme (a 20% expenditure credit), and loss-making, R&D-intensive SMEs can use Enhanced R&D Intensive Support (ERIS).
What Are R&D Tax Credits and Why Are They Important?
The purpose of research and development tax credits is to encourage companies to invest in technical advancement, product development, and innovation. Companies can use these credits to lower their tax obligations if they engage in R&D tax credit qualified activities.
The relief is widely used. HMRC’s latest R&D tax credits statistics, published in September 2026, show that UK companies claimed a provisional £8.2 billion of R&D tax relief for 2024 to 2025, up 5% on the year before, against £51.0 billion of qualifying R&D spend. The number of claims fell 17% to 40,325, which means each claim is worth more on average (roughly £203,000, by our calculation) and HMRC is paying closer attention to higher-value claims. Just 6% of claims account for 69% of the total relief claimed, so a well-evidenced technical narrative and a complete Additional Information Form matter more than ever.
UK tax law sets the rules for R&D claims, and HMRC examines them closely. You must claim the correct amount. If a claim is false or the amount is wrong, penalties and interest can be charged.
Our expert R&D and Tax Dispute Resolution teams can collaborate with your technical teams to test and validate your claim if HMRC has contested it. Before the disagreement spreads to other areas of your tax compliance, it is best to settle with HMRC.
Which R&D Scheme Applies in 2026? Merged RDEC vs ERIS
For accounting periods beginning on or after 1 April 2024, the old SME scheme and the old RDEC scheme were replaced by a merged R&D expenditure credit (RDEC) scheme and Enhanced R&D Intensive Support (ERIS). Company size no longer decides which scheme you use. Your profitability and R&D intensity do. The shift is already visible in HMRC’s 2024 to 2025 figures: £5.9 billion of the £8.2 billion claimed came through RDEC and merged RDEC claims, while SME and ERIS claims fell 36% to 24,570 and were worth £2.3 billion.
| Merged RDEC | ERIS | |
| Who can use it | Companies of any size (including SMEs) | Loss-making SMEs where qualifying R&D is at least 30% of total expenditure |
| How the relief works | 20% taxable, above-the-line expenditure credit | 86% additional deduction plus a 14.5% payable credit on the surrenderable loss |
| Approximate net benefit | About 15p per £1 of qualifying spend at the 25% Corporation Tax rate, or 16.2p at the 19% small profits rate | Up to about 27p per £1 of qualifying spend |
| Loss-making company | The credit is used against other tax liabilities first, then any balance is paid out, subject to a cap linked to your PAYE and NIC (£20,000 plus 300% of relevant payroll) | Paid as a cash credit, subject to the same PAYE and NIC cap |
Worked example, £100,000 of qualifying spend: under merged RDEC the gross credit is £20,000, which is taxable, so a company paying 25% Corporation Tax keeps about £15,000 and one paying 19% keeps about £16,200. Under ERIS, a £86,000 additional deduction increases the loss to £186,000, and 14.5% of that is about £26,970.
Who Is Eligible to Claim R&D Tax Credits in the UK?
R&D tax credit eligibility extends to any company, regardless of size or industry, that makes innovative investments. Understanding what qualifies for R&D tax credits is crucial for determining if your business activities meet the R&D tax credit requirements. Many businesses ask “how can I claim R&D tax” and the answer starts with meeting these fundamental R&D tax incentive eligibility criteria.
Basic R&D Tax Credit Requirements
To determine how to determine R&D tax credit eligibility, your business must meet these essential criteria:
- Your business is a company within the charge to UK Corporation Tax. Sole traders and partnerships cannot claim.
- The project seeks an advance in science or technology, as defined in HMRC’s R&D guidelines.
- Performing R&D tax credit qualified activities.
- There must be technical uncertainty and experimentation in the work.
- The project’s financial risk is your responsibility.
Common Eligible Industries for R&D Tax Credits
The R&D tax credits eligibility spans across various sectors:
- Software and tech
- Manufacturing
- Engineering and design
- Biotech and pharma
- Food and beverage
In HMRC’s latest figures, manufacturing, information and communication, and professional, scientific and technical services together account for 75% of all claims, and London alone accounts for 24% of claims and 30% of the relief value. A claim is worth investigating if your profession entails creativity and using science or technology to solve problems.
What Research Activities and Expenses Qualify for R&D Tax Credits?
Understanding what qualifies as R&D tax credit activities is essential for successful claims. Your company must participate in projects that develop or enhance technology, processes, or products while dealing with technical difficulties. You can check on HMRC Official Website on what activities qualify for R&D Tax Credits.
Qualifying Activities Include
- Developing new products or prototypes
- Improving existing products or manufacturing processes
- Designing or testing new software or systems
- Experimenting with materials or techniques
- Resolving technical uncertainties through trial and error
Qualifying Expenses May Include
- Wages paid to employees for R&D time (including employer National Insurance and pension contributions)
- Materials and supplies needed for the creation of an experiment (consumable items, including some utilities)
- Research expenses under contract (outsourced R&D work) and externally provided workers
- Tools for software development and testing
- Data licences and cloud computing costs used directly for R&D
Watch the overseas and contracted-out rules. Since the 2024 reforms, costs for R&D carried out outside the UK qualify only in limited circumstances, and contracted-out R&D follows specific rules about who can claim. Check both before including these costs.
What Documentation Is Required to Support an R&D Tax Credit Claim?
Proper documentation is crucial for supporting your R&D tax credit claim and passing audit checks. Understanding R&D tax credit reporting requirements and maintaining thorough records makes the difference between approval and rejection.
Key Documents to Maintain:
- Project summaries describing objectives, difficulties, and outcomes
- Time-tracking documents for research and development employees
- Payroll records demonstrating R&D work compensation
- Receipts and invoices for supplies, materials, and contractor fees
- Technical records, including prototypes, test results, design drafts, and source code.
- Meeting minutes or emails on problem-solving and R&D progress
- A clear project narrative for each project: the baseline, the advance you sought, the uncertainties you faced and how you tried to resolve them
Step-by-Step Process for Claiming R&D Tax Credits in the UK
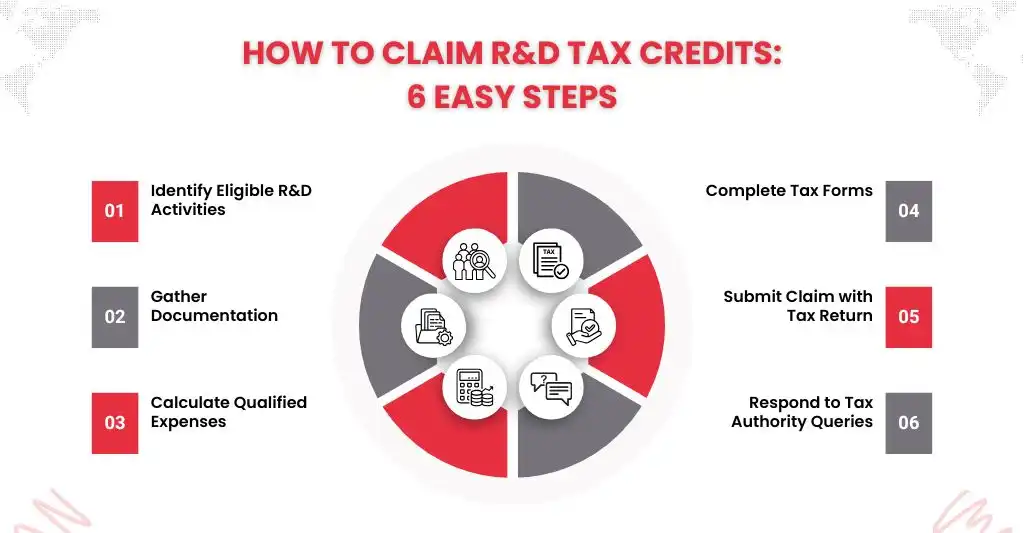
Claiming R&D tax credits can reduce your company’s tax obligation, but it requires careful preparation, precise computations, and comprehensive documentation. You can submit a compelling and compliant claim by following the steps mentioned below:
Identify Eligible R&D Activities
To identify activities that fit the R&D requirements, start by looking at the most recent projects your company has undertaken. Seek employment that:
- Aims to create or enhance a technology, software, procedure, or product.
- Involves problem-solving and technological ambiguity.
- Calls for testing, experimentation, or iterative development.
- To guarantee that all qualifying operations are recorded, involve your financial and technical departments.
Gather and Organise Documentation
It is essential to have documentation to back up your claim and defend it in the event of an audit or review. Keep actual (real-time) records that connect your stated expenses to your R&D efforts.
Key documents may include:
- Technical reports or project descriptions
- Logs of employee time spent on R&D jobs
- Payroll documentation for R&D employees
- Receipts and invoices for supplies or labor performed by subcontractors.
- Test data, source code, or models.
Calculate Qualified R&D Expenses
After qualifying activities have been found, figure out the related expenses. For UK claims, qualifying costs typically include:
- Supplies: Items used for development or research.
- Subcontractor costs: Payments to external parties for research services are known as subcontractor costs.
- Cloud services and software: If utilised for testing or development.
How to File Your R&D Claim with HMRC: Forms and Deadlines
Step 1: Check whether you must submit a claim notification
You must tell HMRC in advance that you plan to claim if you have never claimed R&D relief before, or you have not made a claim in the previous three years. The notification is made online and must be submitted within 6 months of the end of the accounting period you are claiming for. Missing it can make the claim invalid, so diarise the date as soon as your year ends. HMRC accepts a late notification only in very limited circumstances, so speak to an adviser immediately if you have missed it.
Step 2: Complete the Additional Information Form (AIF)
Every R&D claim must be supported by an AIF, submitted online before you file the CT600. If you claim without one, HMRC treats the claim as not made. The form includes the name of the senior officer responsible for the claim, details of any agent, a breakdown of your qualifying costs, and project descriptions that cover at least half of the claimed expenditure. Submit the AIF first, because if it is sent at the same time as the return, HMRC may strip the claim out.
Submit the Claim with Your Tax Return
Prepare your R&D claim and submit it with your Company Tax Return (CT600, The deadline to make or amend an R&D claim is 2 years after the end of the accounting period in which the R&D took place, and this is separate from the normal filing deadline for the CT600 (12 months after the period end). Remember the important dates because late claims will be rejected.
Example: for an accounting period ending 31 December 2026, the claim notification (if needed) is due by 30 June 2027, and the final deadline to make the R&D claim is 31 December 2028.
Working with a tax counselor or R&D specialist will usually take care of this portion for you and guarantee that the submission is timely and proper. If you would like help with your claim, see our Corporation Tax services.
Respond to HMRC Inquiries
HMRC may ask for more details or an explanation after you file your claim, and may open a compliance check. Be ready to:
- Provide proof of your expenditures and actions.
- Describe your cost-calculating process.
- Demonstrate how your work fits the R&D definition.
New in 2026: HMRC introduced a targeted advance assurance pilot in May 2026 that lets eligible SMEs seek clarity on specific complex or higher-risk areas of a claim before submitting it. Ask your adviser whether your project qualifies for the pilot.
How Do You Calculate the Amount of R&D Tax Credit?
The kind of expenses incurred, whether your company is profitable, and (for ERIS) how R&D-intensive it is all affect how much R&D tax credit your company is eligible to receive. The overall method is determining eligible R&D spending and applying a credit rate to those costs.
Identify Qualified Research Expenses (QREs)
These typically include:
- Wages paid to employees who work directly in research and development
- Materials and supplies for prototypes or experiments
- Contract research (a percentage of the money you spend on outside parties)
- Costs of cloud computing and software (if employed in R&D)
Apply the credit rate:
- UK: 20% merged RDEC credit for companies of any size (about 15–16.2% net of Corporation Tax), or up to about 27p per £1 of qualifying spend under ERIS for loss-making R&D-intensive SMEs
Account for Limitations and Adjustments
Grants, subsidies and state-aid limits can affect how much you can claim on funded projects, so check which rules apply. For loss-making companies, the cash you can receive is capped by reference to your PAYE and NIC liabilities, and any unused credit can be carried forward to later periods.
What Are Common Challenges When Claiming R&D Tax Credits and How Can You Overcome Them?
Although there are many advantages to claiming R&D tax credits, many businesses encounter preventable problems along the way. Here are some problems faced and solutions for that.
Misidentifying Eligible Activities: Many companies may incorporate non-eligible tasks or ignore qualified work.
Solution: Use the appropriate R&D definitions in HMRC’s guidelines and involve technical teams as early as possible.
Poor Documentation: Insufficient documentation makes it challenging to support your claim, particularly during an audit.
Solution: Maintain thorough, up-to-date records of R&D initiatives, costs, and employee participation.
Incorrect Expense Calculations: Cost overestimation or underestimation may result in fines or lost advantages.
Solution: Make use of a consistent approach and verify the numbers twice. Think about hiring a specialist or using R&D tax software.
Unfamiliarity with Tax Rules: Due to frequent changes, compliance can be challenging.
Solution: Stay updated on current guidelines or consult an R&D tax advisor.
Delays or Missed Deadlines: A missed claim notification or a claim filed after the 2-year limit can mean losing the relief for that period.
Solution: Be mindful of filing deadlines and begin monitoring R&D at the start of the tax year. Diarise your claim notification date (6 months after the period end) and your final claim date (2 years after it) as soon as the accounting period ends.
Incomplete or inconsistent Additional Information Form: If the AIF is missing or does not match your CT600 computation, HMRC may remove or query the claim.
Solution: Prepare the AIF and the computation together, and have the senior officer named on the form review both before filing.
Including overseas or contracted-out costs incorrectly: These are common reasons claims are challenged.
Solution: Identify where the work was done and who commissioned it before adding these costs to the claim.
What Are the Benefits of Successfully Claiming R&D Tax Credits?
Businesses involved in innovation might gain substantial financial and strategic advantages by successfully claiming R&D tax credits. Beyond just tax savings, these advantages can significantly affect the long-term expansion and competitiveness of your business.
Reduced Tax Liability: R&D tax credits immediately lower the tax liability of your company. This increases profitability by ensuring that a larger portion of your revenue stays with the business. Excess credit can be carried forward to later periods.
Improved Cash Flow: In the UK, loss-making companies can receive a cash credit under the merged scheme (subject to the PAYE and NIC cap), and ERIS can pay more to R&D-intensive SMEs. Even if the company isn’t yet profitable, this brings in money to support continuing operations or new initiatives.
Supports Innovation and Growth: Large-scale development initiatives become more feasible when tax credits are used to lower the cost of research and development. Businesses can put the money they save back into developing new products, employing qualified employees, entering new markets, or developing new technology.
De-risks R&D Investment: The results of research and development are frequently unpredictable. R&D tax credits enable companies to recoup a percentage of their expenses, reducing some of that financial risk and making innovation a more long-term, sustainable approach.
Competitive Advantage: Companies that regularly invest in research and development (R&D) and benefit from associated tax benefits are better positioned to maintain their competitive edge. Stronger IP (intellectual property) portfolios, quicker product development, and improved customer solutions are all examples of this.
Frequently Asked Questions (FAQ)
Are R&D tax benefits available to startups and small businesses?
Yes. Startups and small businesses can claim if they are UK companies carrying out qualifying R&D, even if they are not yet profitable. A loss-making company can receive a cash credit under the merged scheme, and a loss-making SME that spends at least 30% of its total expenditure on R&D may qualify for the higher ERIS support. A first-time claimant usually also needs to submit a claim notification within 6 months of the end of the accounting period.
How long does it take to receive the R&D tax credit?
There is no guaranteed turnaround. Timing depends on HMRC’s workload and on whether it opens a compliance check. Claims with a complete Additional Information Form and a clear technical narrative tend to be easier to process. Your adviser can tell you what turnaround to expect at the time you file.
In R&D claims, what is meant by “technological uncertainty”?
It means the answer to a technical problem is not already known or readily worked out by a competent professional in the field. HMRC’s guidelines refer to scientific or technological uncertainty. Routine work that applies existing knowledge does not usually qualify, but work that needs experimentation to overcome a real technical hurdle can.
What is the deadline to claim R&D tax credits in the UK?
The deadline is 2 years after the end of the accounting period in which the R&D took place. First-time claimants, and companies that have not claimed in the last three years, must also submit a claim notification within 6 months of the period end. The Additional Information Form must be submitted before the CT600.
Are R&D tax credits the same as R&D tax relief?
Yes. People still say R&D tax credits, but HMRC now calls it R&D tax relief. For accounting periods starting on or after 1 April 2024, it is claimed through the merged RDEC scheme or, for eligible loss-making R&D-intensive SMEs, ERIS.
What is the Additional Information Form (AIF)?
The AIF is an online form that every R&D claimant must complete before filing the CT600. It gives HMRC details of the claim, including a named senior officer, a breakdown of the qualifying costs, and descriptions of your R&D projects. Without it, HMRC treats the claim as not made.
Can sole traders or partnerships claim R&D tax credits?
No. Only companies that are liable to UK Corporation Tax can claim R&D tax relief. Sole traders and partnerships cannot, although a limited company owned by individuals can. If you are weighing up incorporation, see our sole trader vs limited company guide.
How much can I claim back through R&D tax relief?
Under the merged scheme the credit is 20% of qualifying spend, which is taxable, so the net benefit is about 15p to 16.2p per £1. A loss-making, R&D-intensive SME claiming ERIS can receive up to about 27p per £1. On £100,000 of qualifying spend that is roughly £15,000 to £16,200 under merged RDEC and about £27,000 under ERIS.
What happens if I miss the claim notification deadline?
If you needed to notify HMRC and missed the 6-month deadline, the claim is invalid for that period. HMRC applies only a narrow exception, so contact an adviser straight away if this has happened.
Conclusion
Whether you’re a major corporation, a growing start-up, or an established SME, claiming R&D tax credits can be a potent way to recover costs, improve cash flow, and reinvest in innovation. Although the procedure calls for thorough paperwork and adherence to HMRC regulations, there may be substantial benefits.
The secret to success is knowing your eligibility, gathering the necessary supporting documentation, meeting the claim notification and Additional Information Form requirements, and properly submitting your claim within two years of your period end. Working with a skilled advisor or accountant can help you maximise your claim while lowering risk if you’re unclear about any step.
Do you still require assistance or have questions about your R&D claim? With knowledgeable advice catered to your sector and corporate objectives, we are here to assist.
Disclaimer: Kindly note this blog provides general information and should not be considered financial advice. We recommend consulting a qualified financial advisor for personalised guidance. We are not responsible for any actions taken based on this content.